3 months Premium FREE
No credit card. No commitment.
Kimberly-Clark Corporation
🇺🇸 KMB · NYSE/NASDAQ
Consumer
Price at analysis: USD 104.82 Current price: USD 101.74 * updated every night
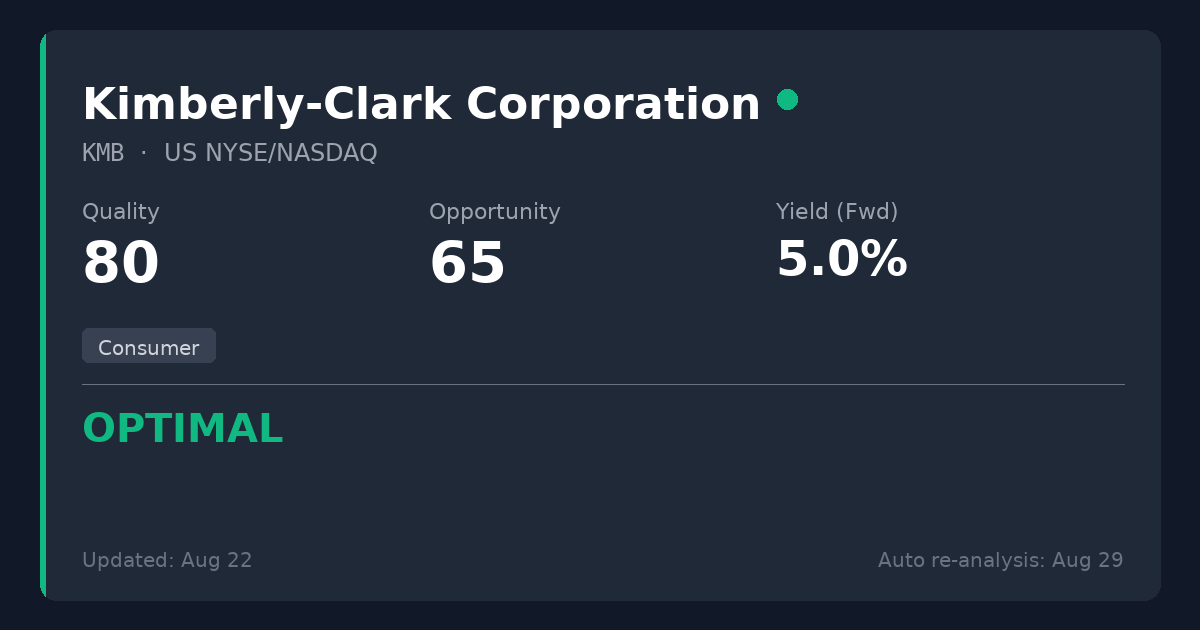
Scores
Key Metrics
Powered by EODHDP/E (TTM)
17.9
P/E (Price-to-Earnings)Shows how much investors pay for each $1 of profit. We display the TTM P/E (Trailing Twelve Months) which uses actual earnings from the last 4 quarters. This is more reliable than Forward P/E which uses analyst estimates.
Calculation: 104.82 ÷ 5.87 = 17.9
TTM period through: 2026-06-30
Forward P/E (estimated): 13.1
Based on analyst estimates
Reference: Provider P/E (Trailing): 19.4
Net Debt/EBITDA (TTM)
1.7x
Latest quarter: 7.0x
Net Debt / EBITDAA leverage ratio showing how many years of EBITDA (earnings before interest, taxes, depreciation, and amortization) it would take to repay net debt. EBITDA approximates operating cash generation. Lower ratios (e.g., <3x) are generally safer; higher (e.g., >5x) may indicate more financial risk.
TTM through: 2026-06-30
Latest quarter (2026-06-30): 7.0x
The quarterly value can spike when quarterly EBITDA is very low (e.g., one-time charges).
Quick guide: <2x manageable, >4x can be risky (sector-dependent).
ROE
1.0%
ROE (Return on Equity)A profitability measure: how much profit is generated from shareholders’ equity. Higher isn’t always better if it comes from high debt.
EV/EBITDA
12.0x
EV/EBITDAA valuation ratio that compares total business value (including debt) to EBITDA. Lower can mean cheaper, but context matters.
Dividend Summary
Powered by EODHDDividend Yield (Fwd)
4.99%
TTM: 5.11%
Dividend YieldThe Forward yield (Fwd) shows the next announced annual dividend / current price — what you'd earn going forward. The Trailing yield (TTM) in the tooltip shows dividends actually paid in the last 12 months. Forward is shown as primary because it reflects the company's current commitment to shareholders.
Forward Yield (estimated): 4.99%
Trailing Yield (TTM, last 12 months): 5.11%
Payout Ratio (Fwd)
87.3%
TTM: 85.9%
Payout RatioDividends as a percentage of earnings. The Forward payout (Fwd) uses the announced dividend divided by actual past earnings (TTM) — it tells you if the company can afford what it promised. Very high payouts can be risky, especially if profits fall.
Announced dividend / actual earnings (TTM)
Payout (Fwd): 87.3%
Payout (TTM): 85.9%
Cash Flow Payout (TTM): 50.4%
FCF Coverage (TTM): 1.53x
Growth Streak
8 yrs
Consec. increases
Div. Growth (5Y)
3.3%
Dividend History
EODHD Dividends API| Status | Type | Decl. Date | Ex-Div Date | Pay Date | Currency | Amount |
|---|---|---|---|---|---|---|
| Forecast* | Quarterly | — | 04 Sep 2027 | — | USD | 1.28 |
| Forecast* | Quarterly | — | 05 Jun 2027 | — | USD | 1.28 |
| Forecast* | Quarterly | — | 06 Mar 2027 | — | USD | 1.28 |
| Forecast* | Quarterly | — | 05 Dec 2026 | — | USD | 1.26 |
| Paid | Quarterly | 03 Aug 2026 | 04 Sep 2026 | 02 Oct 2026 | USD | 1.28 |
| Paid | Quarterly | 14 May 2026 | 05 Jun 2026 | 02 Jul 2026 | USD | 1.28 |
| Paid | Quarterly | 27 Jan 2026 | 06 Mar 2026 | 02 Apr 2026 | USD | 1.28 |
| Paid | Quarterly | 20 Nov 2025 | 05 Dec 2025 | 05 Jan 2026 | USD | 1.26 |
* Extrapolated from past dividend history. Not an official announcement — treat as an estimate, not a confirmed date or amount.
Summary
Kimberly-Clark provides essential household and personal care staples, offering a very attractive 5.11% dividend yield backed by 54 years of consecutive raises. While top-line revenue stagnation and the pending $48.7 billion Kenvue acquisition pose near-term integration and regulatory hurdles, its strong cash flow payout (50.38%) and deeply entrenched brand moat make it a resilient compounder. Worth considering for new positions as a highly reliable income generator.
Sector Context
Kimberly-Clark operates in the Consumer Staples sector, manufacturing essential hygiene and personal care products (Huggies, Kleenex, Cottonelle). For DGI investors, this sector offers the ultimate defensive characteristics, with highly predictable cash flows that easily support multi-decade dividend growth strategies.
Temporary Opportunity Identified
The stock is facing a valuation discount due to top-line stagnation and near-term execution risks surrounding the massive $48.7B Kenvue acquisition and its associated EU regulatory hurdles. These are standard integration challenges for global staples that do not impair the essential nature of the core brands.
📊 Strategy Analysis
- • Highly attractive 5.11% TTM dividend yield backed by a 54-year streak of consecutive annual increases.
- • Solid underlying dividend safety with a Cash Flow Payout of 50.38% and FCF Dividend Coverage of 1.53x.
- • Conservative leverage with Net Debt/EBITDA down to 1.74x, demonstrating consistent deleveraging since 2019.
- • Material reduction in legal risk: The DOJ MicroCool investigation, Huggies PFAS suit, and Cottonelle recall class actions have all been formally settled or dismissed.
⚠ What to Watch
- • Structural top-line stagnation continues, evidenced by a 10-year revenue CAGR of -0.6% and declining revenues over the last 8 quarters.
- • Significant integration and regulatory risk tied to the pending $48.7B Kenvue acquisition, which recently faced extended EU antitrust reviews.
- • The previously established $20M settlement for the 'flushable' wipes litigation was vacated and remanded by an appellate court, reopening this liability.
📊 Historical Trends (10 Years)
Powered by EODHDThese charts show how key metrics have evolved over the past decade, helping you identify if the company is improving or deteriorating.
Debt Evolution (Net Debt / EBITDA)
Lower values are better. A declining trend indicates the company is reducing its debt (deleveraging).
Revenue & Earnings Growth
Consistent growth in revenueRevenue
The money a company brings in from selling its products or services. It’s the top line before costs. (blue) and earningsEarnings (Profit)
What’s left after expenses. Positive earnings mean the business made a profit; negative means a loss. (green) indicates a healthy business. Look for upward trends and recoveries after temporary dips.
Dividend Sustainability (FCF vs Dividends Paid)
Free cash flowFree Cash Flow
Cash left after the company pays for running the business and maintaining it. Often used to fund dividends, pay debt, or buy back shares. (FCFFCF (Free Cash Flow)
Short for Free Cash Flow: cash left after operating needs and maintenance spending., blue) should cover dividends paidDividends Paid
Cash the company paid out to shareholders. It’s not guaranteed and can change over time. (green). If dividends consistently exceed FCFFCF (Free Cash Flow)
Short for Free Cash Flow: cash left after operating needs and maintenance spending., the dividend may be at risk.
Analysis date: 2026-10-17
Disclaimer: This information is for educational purposes only. Not financial advice.